
Where the Next Phase of International Education Growth Will Come From
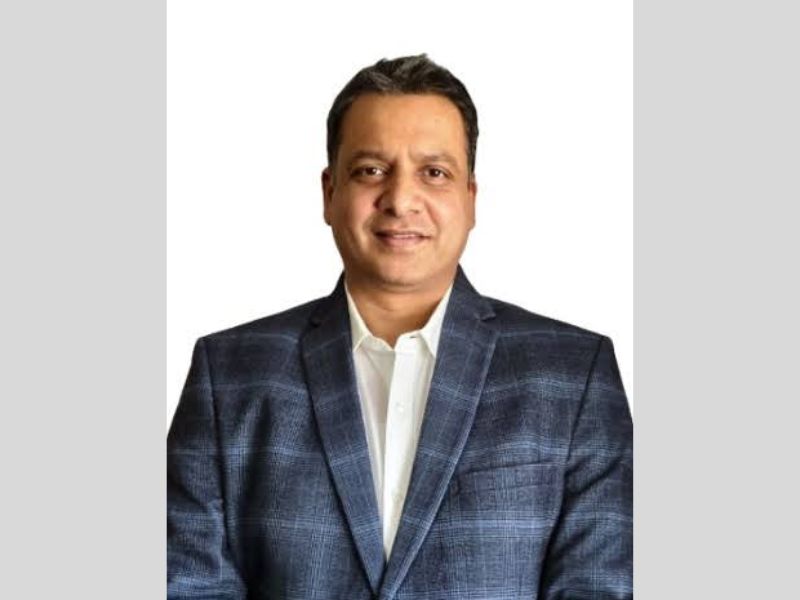
– Dr Vikash Agarwal, Chairman & Managing Director, Crizac
International education is moving through a period of real adjustment. Tightening visa rules across Canada, the UK and the US, rising costs and currency pressure have changed the shape of a market that grew steadily for a decade. Many institutions and agencies have responded by pausing expansion and waiting to see how things settle. That caution is a reasonable first instinct, but history suggests it isn’t the most rewarding one. Periods like this usually decide market position for the decade that follows, and organisations that keep building through the uncertainty tend to be the ones leading once conditions stabilise.
Downturns Are When Market Position Gets Decided
In a booming market, every serious player spends aggressively, and growth masks inefficiency. A slower market changes that arithmetic: as cautious competitors pull back, the cost of reaching high-intent students falls, experienced talent becomes easier to hire, and university partners start looking for well-capitalised, reliable partners to plan around the change together. Continuing to invest while others wait isn’t recklessness; it’s how ground gets taken affordably before the next growth cycle begins.
The Market Isn’t Shrinking. It’s Being Repriced
The numbers point to recalibration, not collapse. India’s Ministry of External Affairs data shows just over 1.25 million Indian students studying abroad in 2025, a 5.7 percent dip from 1.33 million in 2024, the first such dip in three years, driven largely by tighter financial requirements and post-study work changes in Canada and the UK.
This isn’t weakening ambition; it’s redistribution. Parliamentary data shows Germany and Ireland gaining students as families find comparable outcomes at lower cost, even as Canada, Australia, the UK and the US collectively saw roughly 173,000 fewer Indian students. Foreign university campuses now operating within India, from Deakin and Wollongong at GIFT City to Southampton in Gurugram, offer comparable degrees at 40–70 percent lower cost, though early enrolments remain modest. The market hasn’t shrunk so much as become more discerning and more spread out.
What Families Are Actually Asking Now
Economic pressure changes how a decision gets made, not whether it gets made. During the boom years, a country’s popularity and a university’s ranking did most of the persuading. Today’s families ask sharper, financial questions: What does the post-study employment picture look like? How long will the loan take to repay? How predictable is the visa pathway two or three years out? Generic pitches no longer hold up. Hyper-specific career mapping and a return-on-investment model that families can interrogate do.
Trust Is the Asset That Compounds During Uncertainty
When policy shifts and financial risk rises, families gravitate towards institutions that can show they’ll still be there in three years. Strengthening compliance systems, maintaining an operational footprint rather than scaling back, and holding quality standards steady signal staying power, and trust built this way is far harder for a well-funded competitor to buy back later.
The Structural Floor Beneath the Cycle
It’s worth separating the cyclical dip from the underlying trend. Government estimates put Indian students’ annual overseas education spend at close to $70 billion, and QS’s Global Student Flows research projects sustained outbound growth of around 4 percent annually over the coming decade. What’s changing is where that demand originates: students from Tier-2 and Tier-3 Indian cities now account for roughly 79 percent of applicants, with Tier-3 cities alone at around 46 percent, a structural shift creating a near-permanent floor under long-term demand.
Where the Next Phase of Growth Actually Comes From
Volume-led recruitment worked when the pipeline grew every year; it works far less well once that pipeline tightens. The more resilient path runs through transnational education and structured articulation models, arrangements where students complete part of their coursework locally before transferring abroad, lowering the upfront barrier while securing a guaranteed progression abroad.
The Way Forward: Not All Investment Is Equal
This isn’t an argument for spending indiscriminately. Chasing the same shrinking applicant pool with a bigger paid-media budget isn’t conviction; it’s optimism outrunning the numbers. What actually compounds is less glamorous: compliance systems built ahead of regulation, verification infrastructure that holds up to visa scrutiny, and university partnerships built for the long term.
Organisations that pause entirely risk losing relevance by the time the market strengthens; those that spend without discipline risk running thin before it does. The ones that come through stronger sit in the middle. The sector has always been selling a credible, well-supported route to a better future, and the platforms still investing in that route through this period of change will look, by the time the headlines call it a recovery, like the obvious, safest choice, precisely because they never stopped acting like one.






Add comment